Latest Post
Showing posts with label Deviden and Income. Show all posts

Retail REITs Outperform: Some Things Can't Be Replicated Online


A few days ago, Jeff Jordan posted a Seeking Alpha article, Why Malls Are Getting Mauled. As an expert in e-commerce (Jordan managed three e-commerce businesses), the author argued that the "brick and mortar" model is doomed and "rapidly declining demand for real estate amid growing supply is a recipe for financial disaster." The primary thesis for the author's argument is that:
Online retailers are relentlessly gaining share in many retail categories, and offline players are fighting for progressively smaller pieces of the retail pie.
Recently I wrote about the "brick and click" concept in a Forbes.comarticle and as Bobby Taubman, CEO of Taubman Centers (TCO) explained to me that retailing is an evolutionary model and today consumers are attracted to a variety of merchandising channels, not just e-commerce. As Taubman explained:
The best retailers touch their customers seamlessly whether through e-commerce, catalogs, direct mail or brick and mortar. Brick and mortar enables retailers to holistically present and establish their brands, create an experience that inspires customers, and allows them to socialize and interact with others. Technology has improved the customer experience at all levels - the front of the house, the logistics chain, its efficiency and pricing, and customer knowledge and service. Social media will continue to enhance the connectivity of the customer and retailer, but in this omni-channel world, thebrand is more important than ever.
In the same Forbes.com article, I asked Steve Tanger, CEO of Tanger Factory Outlets (SKT) for his perspective on e-commerce and he summed it up as follows:
Obviously, the convenience and 24/7 availability of e-commerce resonates strongly with consumers, but while online and mobile sales continue to grow, I do not believe that it takes away from consumers' excitement over visiting brick and mortar shopping centers. At Tanger Outlets, we are continually bringing in more in-demand designer and brand-name tenants to provide in-season and on-trend merchandise for our shoppers. Outlet centers provide a one-stop shop that offers great brands at a value price, in one location, in contrast to shopping online where consumers have to search for deals for their favorite brands individually. We also understand that the shopping experience itself is as important as the products that our tenants sell, which is why we fill our centers with dining options and often host concerts or special events at our properties. We want to ensure that we provide those traveling to visit our centers a unique and exciting shopping experience that cannot be replicated online.
Another veteran REIT CEO Dave Henry, with Kimco (KIM), provided me with his thoughts on the value for the traditional brick-and-mortar model:
It is increasing clear, with the striking success of Apple Stores, that product manufacturers (even Amazon in due course) need physical showroom space and stores in high-traffic retail centers. Combined with the growing demand for neighborhood goods and services of all kinds - restaurants, health clubs, theaters, etc., - together with an increasing population, very limited new supply, and the strong probability that e-commerce retailers will have to collect sales taxes, the future continues to be bright for brick-and-mortar stores.
Actions Speak Louder Than Words
Let the numbers speak from themselves. Starting with the retail REIT sector - a $137 billion dollar industry - that includes dominant landlords like Kimco, Taubman Centers, Simon Property Group (SPG), Tanger Factory Outlets, Regency Centers (REG), and Weingarten Realty (WRI). In addition, there are some growing small-cap REITs like Excel Trust (EXL), Retail Opportunity Investments Corp. (ROIC), and Whitestone (WSR).
As of November 30th, the retail REIT sector produced average year-to-date total returns of 23.61%. Breaking that down, the shopping center sector returned 23.03% and the regional mall sector returned 24.13% (source: NAREIT). In addition, the retail sector outperformed all of the major REIT sectors.
Let's take a look at the nation's largest shopping center mall operator,Simon Property Group (SPG). The $48.3 billion (market cap) REIT recently announced exceptionally robust funds from operations (FFO) performance of $1.99 per share, up 16.4% from the third quarter of 2011. Year-to-date, Simon's FFO was almost $2.1 billion or $5.70 per share, up 14.7% over 2011.
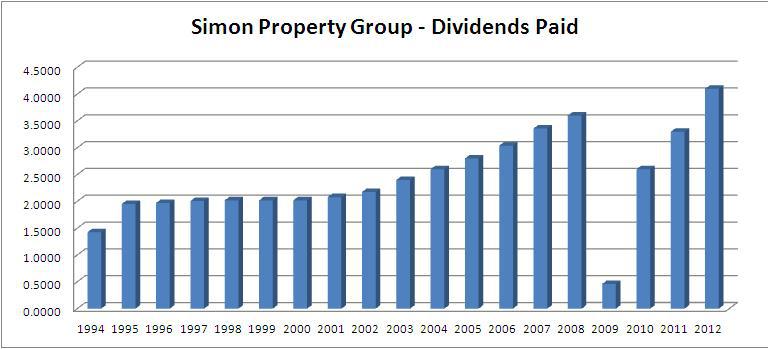
Simon also recently announced the fifth consecutive increase in quarterly dividends from $1.05 to $1.10. The total dividend paid in 2012 is $4.10 as compared to $3.50 per share paid in 2011. That represents an increase of 17.1%. In fact, in this year alone, Simon has increased its dividend by 5 cents a share in all four quarters and Simon's dividend is now 22.2% higher than it was immediately prior to the great recession. This is the highest increase among Simon's retail REIT peers, the second-highest among all S&P 500 REITs behind Public Storage (PSA).
Amazingly, Simon's 2009 dividend deserves to be highlighted. Although the company did stop paying a dividend then, it paid the remaining dividend in stock, which took off like a rocket that year, and ended up being over $4.20 per share by the end of 2009.
(click to enlarge)
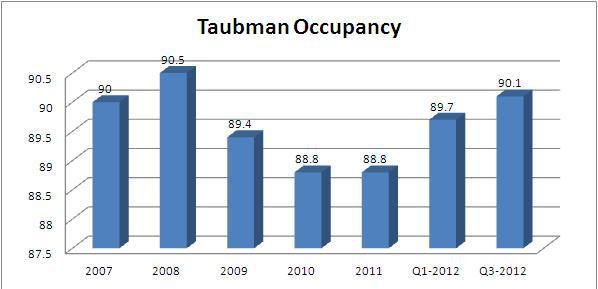
So what about the luxury brands? Or, the luxury brand landlord, Taubman Centers? What happened to Taubman during and after the Great Recession? Occupancy is looking good now (Q3-12 occupancy is 93%). Here is a snapshot of the company's occupancy history:
(click to enlarge)
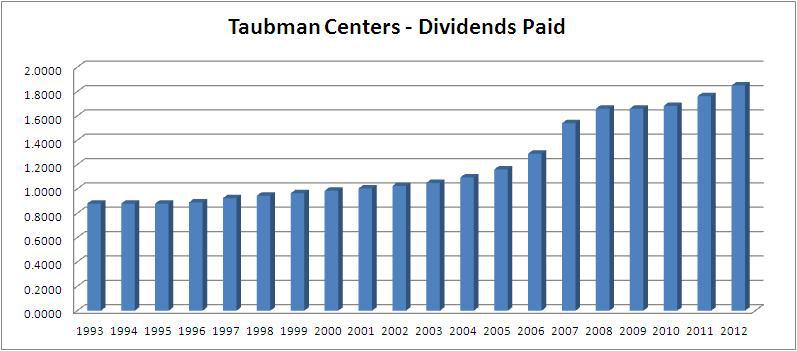
Taubman, with a $4.85 billion market cap, has returned 30.23% year-to-date and the mall sector REIT has an amazing track record of NEVER cutting its dividend. Taubman's current dividend yield is 2.37% and here is a snapshot of the company's sustainable dividend record:
(click to enlarge)
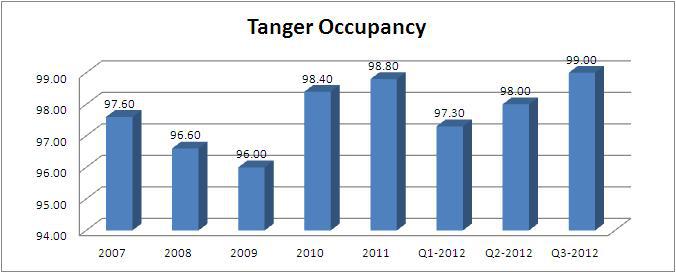
Tanger Factory Outlets is simply one of the best examples of "brick and mortar" success on the planet. In the latest quarter (Q3-12), the $3.205 billion (market cap) REIT had 99% occupancy with literally a "waiting line" for tenants. Take a look at this occupancy snapshot:
(click to enlarge)
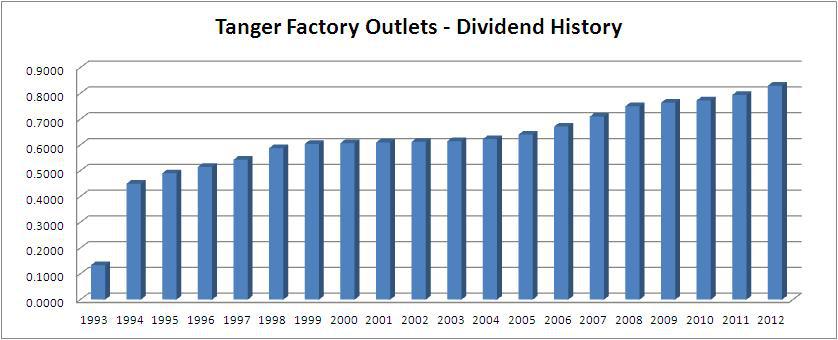
Tanger is also a few weeks away from being inducted into S&P's Dividend Aristocrat club (see article I wrote here). That means that Tanger will have paid consistent and increased dividends for 20 years in a row. This record is a true indicator of the success of the "brick and mortar" model and also a clear example that the "shopping experience cannot be replicated on-line."
(click to enlarge)
In summary, and as I wrote in the above-referenced Forbes.com article:
Despite these few dire examples, retail as a category is healthy. Retail sales at many brick-and-mortar stores are solid, led by specialty-apparel chains and discounters, with department store sales growing, but less robustly. TJX, Target, Wal-Mart and Costco (COST) are thriving, and sales at upscale retailers Saks (SKS) and Nordstrom (JWN) are also good. Even the recently-struggling GapInc. (GPS) seems to have staged a successful turnaround, in part by creating a successful Mad Men collection at their Banana Republic stores. By offering the trifecta of price, selection and service, or by creating a unique brand position where product appeal trumps price sensitivity, these successful retailers remain relevant.
Clearly the retail sector is healthy and intelligent investors must recognize that e-commerce is simply an extended storefront for retailers to expand their businesses and provide "enhanced connectivity." Malls are not dead and innovation is alive and well. Don Wood, CEO of Federal Realty (FRT) explained (in the Forbes.com article) the concept as follows:
The mix of retailers in that center - We call that the process of "merchandising the center," - is more important than ever and needs to be far more "experiential" to consumers than in the past. Unique and well-run food uses are playing a bigger and bigger part in the mix as are tenants serving changing consumer habits in a faster-paced and highly technology-driven world.
Note: Federal Realty has been a REIT for 50 years and the $6.69 billion (market cap) REIT has paid and increased dividends every year for 45 years in a row. No other REIT has come close to that track record.
The success of the retail REIT sector provides the best example that e-commerce is not a threat but a complement. The retail REIT industry is "alive and well" and there are many quality REITs that I will continue to recommend for investors, young and old. As I wrote:
It is clear that many of the best retailers and shopping center owners are focused on giving consumers more than just an outlet to purchase goods. Beyond the basics, they are focused on creating positive, exciting, interactive experiences by leveraging their physical presence and the convenience of technology… and whatever inventions in the way humans live - and shop - develop in the coming decades.
(click to enlarge)
Source: SNL Financial
 

Teekay Tankers Ltd. - An Alternative Analysis


This is a response to Douglas E. Johnston's recent, well-reasoned article on Teekay Tankers Ltd. (TNK) here. In the article, Mr. Johnston makes the bullish case that TNK is now cheap with limited downside risk and substantial upside as the tanker market corrects over the next 2 to 3 years. He believes the company will withstand the current low spot and time charter ("TC") rates through 2014, as it has a strong balance sheet and it should generate enough cash to cover its operating expenses and debt repayments. He sets out his assumptions for a discounted cash flow analysis that comes up with a $5-6 current valuation. He believes that the current actual book value of the company is around $4, not $7.90 per GAAP numbers, based on the current value of the fleet.
I have been watching this stock off and on for about 2 years now and looking for a point to get in. In preview, I believe there is still significant downside at this time, and there is a high degree of uncertainty about the future of the tanker market, so now is not the time to jump in.
Let's start by looking at the company's strategy. The tanker market and the shipping market in general are highly volatile. TNK seeks to mitigate the downturns of the market by having a portion of its ships under TC to provide steady revenues. Of the 28 owned vessels, 15 are currently under TC at rates about 60% above 3Q spot prices, which are typically the lowest of the year. The other 13 vessels are deployed in ship pools that maximize spot charter revenues. The goal is to have this mix of revenues allow TNK to survive in depressed markets and excel in high rate environments. The TK group (TK) is an excellent operator, with extensive experience in all types of markets. This strategy should work, unless there is an extended period of low rates and the TC's expire, forcing those ships into lower rate spot pools that do not generate sufficient cash flow to cover operating expenses and debt service.
The real money in shipping is made by buying ships low at distressed prices and selling in strong markets when rates and ship values are high, in short classic value investing. Extraordinary returns are not made from cash flow. Investing in ships is the same as investing in real estate. One buys the asset cheaply and attempts to generate sufficient cash flow to pay operating costs and debt service until the asset appreciates. This is where the great shipping fortunes have been made.
Shipyards are subject to similar volatility. When demand is low, they drop prices significantly in order to keep some production going, so they can cover fixed costs. Similarly, prices of used vessels drop significantly in times of low demand. The equity investor may be able to make outsized returns by investing in shipping companies at low asset valuations and where the company has the cash flow generating power to survive the low point of the cycle and benefit from the upswing in rates and new build costs. Higher new build costs translate into higher used ship values. This strategy requires discipline and patience. One has to buy at the bleakest point and be prepared to wait out a turn in the market. It is impossible to predict the timing of a turnaround; however one can assume that one will happen at some point.
In "normal" environments, spot rates are higher than long-term TC rates; however in today's market, the situation is reversed. The industry suffers from over capacity as a result of over building 3 to 5 years ago in anticipation of rapidly growing emerging market demand (in China) and a strong world economy. Today's rates are not only depressed; so are ship values. This is what makes TNK an interesting investment. However, based on 3Q numbers, TNK is barely generating any distributable cash flow ("DCF") after reserves for dry-docking and debt service. 4Q rates and revenues are predicted to pick up due to seasonal demand, but the company expects the rate increases to be very short-lived.
More importantly, the remaining term of the TCs is only about 1.5 years. Seven of the 15 ships under TC will expire in '13 and enter the spot market unless their charters are renewed. Currently, TC revenues account for 63% of the total. Spot rates in the 3Q averaged $12,900 per day or 63% of the average rate of $20,500 on the TC fleet. If these ships fall into the spot pool by the end of '13, quarterly TC revenues will decline from $32m to $20m, and TC revenues will account for only 52% of total revenues. A $12m drop in quarterly revenues will cause DCF to be negative by approximately $10m (3Q DCF was $1.3m).
While supply and demand may come more into balance in '13, it is doubtful spot rates will return to sufficient levels to return the company to positive DCF. This is a worst case scenario, and TNK may be able to extend charters, although probably at lower rates. Looking at it another way, cash flow from operations in 3Q was $20.3m vs total dividends paid of $30m, and this does not take into account debt service or dry docking. TNK does have over $300m in liquidity between its cash and revolving credit line, which does not expire until 2017. However, the company is not self-sustaining at this moment.
One way to confirm how bad the market is now is to look at Nordic American Tankers (NAT). This company's fleet is all Suezmax ships on spot hire and has almost no debt. Their strategy is ride the spot market without using leverage and buy ships in down turns and reap in good times. NAT has negative operating earnings and negative EBITDA. They are bleeding cash and borrowing to pay the dividend. Not a sustainable model.
Analyzing the net asset value is another way to view whether the stock price is really cheap and sufficiently low to provide a margin of safety. I based the current fair market value of TNK's fleet on numbers from a Morgan Stanley shipping industry outlook from January 2012, admittedly a bit out of date. Ten year old Suezmax $31m, Aframax $21m, MR $18.9m, and LR2 $22m. Adding up the values of the 28 ships plus the value of the other assets and subtracting debt and other liabilities, I come up with a revised book value of a bit less than $1 per share. This compares with a GAAP book value of $7.90. Clearly, my numbers are old and could be underestimated. I am trying to get updated numbers. But, to get to $4, the value Mr. Johnston uses, I would have to increase the value of the ships by 40%. Therefore, I believe there is meaningful downside from the current price of $2.80 and insufficient margin of safety.
In conclusion, I think this company may be the best operator in the tanker market. They employ a conservative strategy designed to get them through bad times like the present. I think there has to be upside from here 1 to 2 years out. However, I do not think there is a sufficient margin of safety from the NAV, there may be deteriorating revenues and cash flows in '13 if TC are not renewed and there is a possibility that the world economy and that of China may not grow as much as anticipated (to say the least). So being the conservative guy that I am, I am going to wait for greater clarity on renewals or for the stock price to decline closer to NAV. I write this in the spirit of collaboration and welcome any comments or thoughts, especially about my NAV calculation. By far, my greatest errors are ones of omission not commission so this may be another example. Thanks again to Douglas Johnston for taking the lead with a very well reasoned analysis.
 

What Happens When Non-Spouses Inherit My IRA?


In the previous two articles, linked here and here, I started with some initial questions about IRAs and spent an entire article talking about the various options our spouses have when she/he inherits the IRA. But what about when non-spouses, including charities, handle this gift you gave them?
My answers will be as if the IRS will make the strictest interpretation of what they originally wrote. I believe they have flexed the rules a little (like when you have multiple beneficiaries of various ages) on splitting the IRA after your death, but I would rather say you be prepared for the worst and handle your matters with no confusion now while you are alive versus creating a mess that you will not be able to fix post-mortem.
Two other key points that don't relate to the rest of the article I will discuss now. If you are the inheritor of an IRA, you have up to 9 months to accept the gift or not. If you accept the gift, your first required RMD (I will talk about all distributions as taking just the minimum, but you can always take more), will be the year after the person has died. If you recuse yourself from the gift (which should be filed with the brokerage firm along with probate court), it will then go to the next beneficiary stated on the IRA form.
The second point is if the IRA owner had died before taking their RMD for the year, the inheritor will be required to take their respective RMD on the IRA owner's behalf. So if someone who is 83 years old passes away in January 2013, and did not take their RMD for the year, the inheritor will take the required RMD on their behalf (and the inheritor will file it on their tax return) and then all subsequent RMDs starting in 2014 will be based on the inheritor's life expectancy table. This will (hopefully) become much clearer in the examples below.
To try and put some names to our example, we have the following family and ages as of 2012:
Doctor Dividend, IRA owner, Age 75, value of IRA 12/31/2012: $900,000 and value of Roth IRA: $450,000
Penny Dividend, Wife, Age 74
Quarter Dividend, Child Age 44
Shekel Dividend, child of Quarter, Age 6
Rupee Dividend, child of Quarter, Age 1
Nickel Dividend, Child Age 42
Sacagawea Dividend, Child Age 39
Lira Dividend, Child of Sacagawea, Age 3
Charity: March of Dimes (could it be anything else?)
When the inheritor is not the spouse, RMDs are required. Period. Even on Roth IRAs, they are required. The Roth RMDs are tax-free, but they are still required. I cannot stress this enough that they are required or the inheritor will get hit with a massive tax penalty. The amount is determined by Table One of the IRS Life Expectancy Tables, linked here. You only need to look at this chart once for the rest of the distributions.
In this article, Doctor and Penny Dividend have decided that the IRAs will go to the children.
Scenario 1: Doctor Dividend fills out the brokerage form that says that Quarter, Nickel, and Sacagawea are the beneficiaries of the ONE IRA in"equal share," so each will get $300,000 from the IRA and $150,000 for the Roth. When Doctor Dividend dies (for the remainder of the article he has passed away in 2012), by strict IRS code, what is the RMD taken by each child?
Answer: You use the oldest inheritor as the basis for all RMDs, which is Quarter. He will be 45 in 2013, which is a divisor of 38.8 (linked here, see Table One on Page 86). So, each child will take the following RMD for 2013:
$300,000/38.8 = $7731.96 (taxable)
$150,000/38.8 = $3865.98 (tax-free)
For all subsequent years, you subtract ONE from the divisor (2014 = 37.8; 2015 = 36.8; etc.) until the account is extinguished. That is why I can say with confidence that no inherited account will last beyond 83-85 years of age of the beneficiary when you give it to someone under 50 years old. In this easy scenario, with the children close in age, the divisor is not a stretch IRA killer (Sacagawea's divisor would have been 43.6). But what if the beneficiaries were of massively different ages?
Scenario 2: Equal shares to Shekel, Rupee, Nickel, and Lira. What is the RMD taken for each inheritor?
Answer: The oldest inheritor is the basis for all RMDs, which would be Nickel (divisor for 43 years old = 40.7). But look what Doctor Dividend just did! He shrunk how long the grandkids could stretch the IRA by 36 YEARS! Shekel, at the ripe old age of 7, would have been able to stretch these IRAs for 75.8 years. Remember, after the first year, we just subtract one for every subsequent year thereafter. Thirty-six years of compounding just died with the doctor. Let's go through two more scenarios before I show you how to fix this problem:
Scenario 3: Equal Shares to Quarter, Nickel, Sacagawea, and the March of Dimes. What is the RMD for 2013?
Answer: You use the oldest inheritor as the basis for all RMDs. But we have a problem. The March of Dimes is not a person, so it does not have a life expectancy. The old rules apply where the inheritors have 5 years to exhaust the account (Note: The 5 years does not have to be taken in equal amounts. You could wait until the fifth year and remove everything then). The March of Dimes does not care, because it takes all the money it is given and pays no taxes, but the 3 children will care because instead of having 38.8 years to stretch it, like Scenario 1, they are now down to 5. Thanks Dad!!
Scenario 4: Like Scenario 1, where Quarter, Nickel, and Sacagawea are equal share inheritors, but Doctor and Quarter die together in an auto accident. Who gets what and what is the RMD?
Answer: The sad truth in this scenario is that Shekel and Rupee get nothing and Nickel and Sacagawea get the IRAs as a 50:50 split. So the RMD would be based on Nickel at the age of 43:
$450,000/40.7 = $11056.51 taxable
$225,000/40.7 = $5528.26 tax-free
The two children are not required in any way, shape, or form, to give their niece and nephew anything. It would have been different if two little Latin words were included on the beneficiary form. Those two words are: "in stirpes," which loosely translates as "within the family line." If those two words were on the form after each beneficiary's name, then Shekel and Rupee would have gotten the share, as I am sure their grandfather would have intended.
The real question that should be percolating in your mind is: How do I not screw this up and everyone gets what they should? The easiest answer is to make multiple IRA accounts with each person their own beneficiary. If we did that in scenario 3 (the charity example), the following would have occurred:
IRA 1 to Quarter (the only primary beneficiary on this IRA): $225,000/38.8 = $5798.97
IRA 2 to Nickel: $225,000/40.7 = $5528.26
IRA 3 to Sacagawea: $225,000/43.6 = $5160.55
IRA 4 to March of Dimes: $225,000 taken immediately due to no taxes
I did not show the Roths, but the same rules apply to splitting the account and distributions. Sacagawea would have 5 more years to stretch the money in this instance versus Scenario 1, because it is only her longer life expectancy that is being used for the calculations and not that of her older brother.
I'll end this article with one last twist: What if the inheritor of the IRA dies? Sacagawea inherits her father's IRA at age 40 and went to Table One and used the 43.6 years, and has followed the RMDs as described for the last 20 years. She put the primary beneficiary of this inherited IRA as Lira. At 60 years old, Sacagawea dies (she took her RMD for the year and the IRA is now valued at $750,000) and Lira is now 23. What does Lira do?
Answer: Lira DOES NOT go back to Table One and use her Life Expectancy. You only use Table One if you are a direct inheritor of the deceased's IRA. What Lira does is continue on the path of her mother's life expectancy. Here is what I mean in numbers:
At age 60, Sacagawea used the divisor of 23.6 for her RMD (43.6 originally - 20 years of taking RMDs) that she took for the year before she passed on. Lira will use 22.6 the next year. Hence, Lira's RMD will be:
$750,000/22.6 = $33185.84
Lira will continue to subtract one each year just like her mom has done until this account is exhausted. Any IRA that Lira directly inherits from her mother, she would use Table One. And of course, she would retitle the account as follows:
Sacagawea Dividend, IRA (deceased, October 12, 2033) F/B/O Lira Dividend, beneficiary
And name her own beneficiaries in case Lira passes on before these 22.6 years are exhausted.
To conclude, I hope this was helpful. As I said at the beginning of the article, I believe the IRS has allowed one IRA to be split post-mortem so each person uses their own life expectancy, but I would get the help of an IRA advisor to clarify and I would rather present the worst case scenario if things went terribly wrong. It makes matters much easier if you have several IRA accounts and each lineage is separate, making the hairiest part of inheritance, the split of who gets what, easily known to each beneficiary. And do make sure you have contingent beneficiaries as well for the flexibility of recusing the primary beneficiary (your child) so the IRA could be stretched to its maximum potential (a grand or a great-grandchild). Now that could be one heck of a gift.
 

Is LTC The Right REIT For Me?


With the increasing fear of the unknown last chapter of the Fiscal Cliff, it is clear that REITs are beginning to look like the "goose that laid the golden egg." As we all know, there is nothing new or significant pertaining to REITs, except that non-REIT dividends are likely to revert to being taxed at ordinary rates in 2013.
As the Bush Tax Cuts expire (at the end of the calendar year in 2012), REIT income will soon be on a much more level playing field as compared with non-REITs whose tax advantage is likely to be removed. Hence, REITs will not be affected and that will make the asset sector even more attractive, compared to C-Corporations.
As I wrote in a recent Seeking Alpha article (Why Sound Investors Should Consider My "Bond-Proxy" REIT Picking Strategy):
Triple-net REITs are generally at the top of most investor wish lists - and for the same reason - many of the newest proposed REITs have considered entry to the durable triple-net income sub-sector. Among the new triple-net candidates include Lamar (LAMR) - see articlehere, Penn Gaming (PENN) - see article here, and Iron Mountain (IRM) - see article here. The "bond-like" net lease alternative is attractive not just because of the relative simplicity of being the landlord of a single-tenant triple-net leased investment, but also because of the security offered by the repeatable income fundamentals of these properties.
As I was writing the above-mentioned article, I ran across a REIT that seemed to provide an interesting value proposition. In addition, I wanted to determine if there is another healthcare REIT that I could include in my upcoming Forbes newsletter "sleep well at night" portfolio. As I wrote (in the above-referenced Seeking Alpha article):
In general, the healthcare REIT occupancy rates are more closely aligned with the office sector rates; however, the strong demand in medical space (and low new supply) has enabled healthcare occupancies to become more closely aligned to the triple-net REIT sector. Clearly the strong demand in the stand-alone asset class is what makes the "bond-like" classification so attractive.
Is LTC the Right REIT For Me?
LTC Properties, Inc. (LTC), based in Westlake Village (California), is a healthcare REIT that invests primarily in the long-term care sector of the healthcare industry through the origination of first mortgage loans and acquisition of properties that are leased to numerous long-term care providers. LTC was incorporated on May 12, 1992 in the State of Maryland and commenced operations on August 25, 1992. LTC invests primarily in senior housing and long-term healthcare property types including skilled nursing properties (or SNF), assisted living properties (or ALF), independent living properties (or ILF) and combinations thereof.
As of the latest quarter (Q3-12), LTC owned assets of approximately $710 million with total debt of around $224 million. The majority of LTC's assets are invested in skilled nursing (54%) - followed by assisted living (36%), other senior housing (18%), and schools (1.4%).
(click to enlarge)
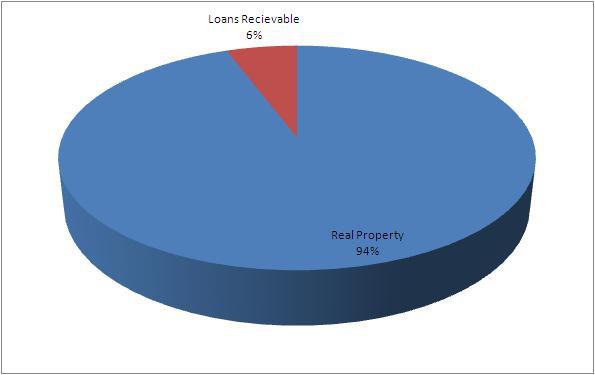
Most of LTC's assets are invested in real property (94.3%) with a small amount invested in loans (5.7%).
(click to enlarge)
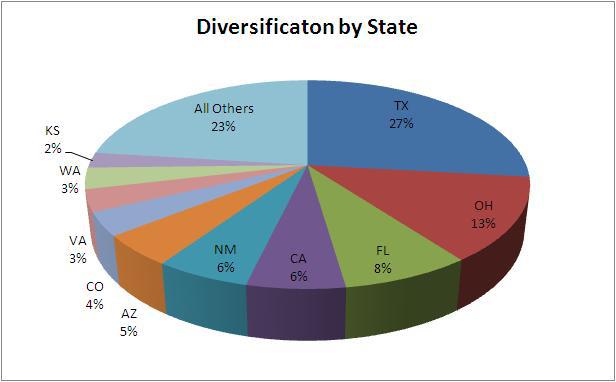
LTC has a diverse portfolio of assets scattered across 35 States. Texas has the highest concentration (26.8%), followed by Ohio (13%), Florida (7.9%), and California (6%).
(click to enlarge)
Here is snapshot (chart) of LTC's geographic diversification (by State) and by gross investment:
Does LTC Have a Sustainable Income Model?
About a month ago, I wrote a Seeking Alpha article on Omega Healthcare Investors (OHI). While researching that article (and since Omega has around 97% concentration in skilled nursing operators), I decided to examine the potential risks that could impact most (from the Affordable Care law) and specifically, the operators that receive reimbursements from Medicare.
In particular, skilled nursing facilities (nursing homes) draw 40% to 50% of their reimbursements from Medicare and that appears to be the biggest threat for healthcare REITs that derive income from that sector.
Like Omega, LTC has a majority (54%) invested in skilled nursing and both Omega and LTC house their tenants under triple-net leases. Omega is much larger in size ($2.643 billion market cap) compared to LTC ($1.063 billion market cap) and Omega has 460 properties (435 skilled nursing properties) compared with LTC's 207 properties (89 skilled nursing properties).
The biggest threat for the long-term care sector is the possibility that their tenants could be impacted by the operators' health and ability to pay rent. In the case of Omega, there are 44 different operators, the largest of which is Communicare (36 facilities and 11.4% of rent) - followed by Sun (40 facilities and 11.1% of rent), and Airamid (38 facilities and 7.9% of rent).
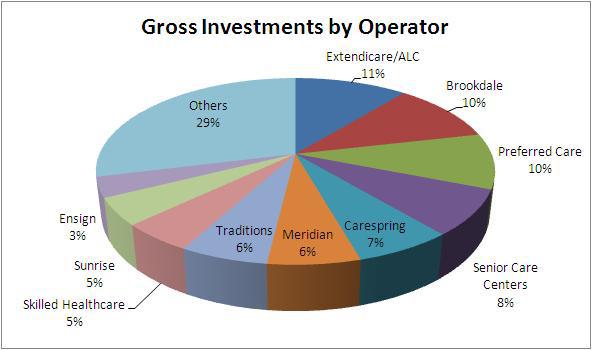
LTC has 32 operators including skilled nursing tenants like Ensign Group (ENSG), Skilled Healthcare Group (SKH), Preferred Care, Sun Healthcare (SUNH), and Senior Care Centers. LTC's largest assisted living tenants include Brookdale Senior Living (BKD), Emeritus Senior Living (ESC), Assisted Living Concepts (ALC), Senior Lifestyle Corp., and Sunrise Senior Living (SRZ).
(click to enlarge)
Here is a snapshot of LTC's gross investment by operator:
(click to enlarge)
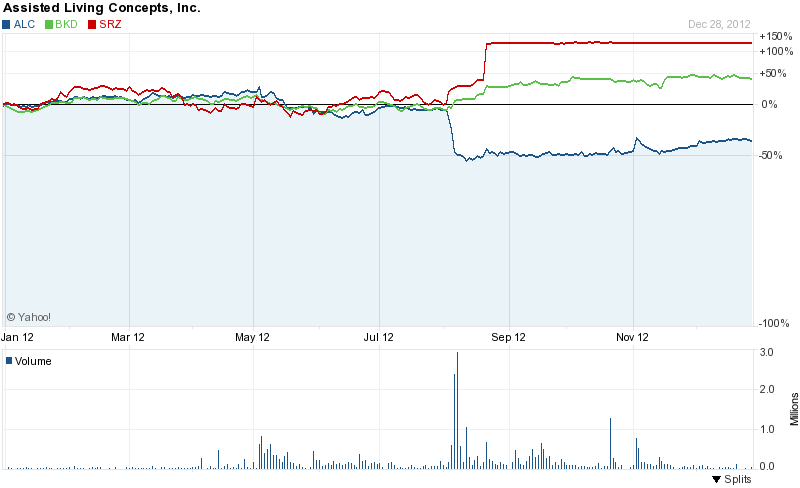
Upon further review, it appears that one of LTC's primary tenants,Assisted Living Concepts is having trouble. While Sunrise and Brookdale have traded up in recent months, ALC shares have dropped over 42% this year. The company has had a losing streak of losses with declining occupancy and revenue. Earlier this year, the CEO was booted and the company is trying to find its footing by refurbishing facilities and paying down debt.
(click to enlarge)
Clearly Obamacare adds to the drama as many healthcare operators are continuing to face pressure with declining profitability. I think that ALC is an isolated example; however, as many of the operators (like BKD and SRZ) are reporting positive and improved earnings.
(click to enlarge)
During LTC's recent earnings call, Wendy L. Simpson, CEO and President, explained the impact (or lack of impact) on ALC:
As I've said in the past, then I reiterate now, there is no reason to assume that LTC will not collect all rents due us under our two master leases with ALC/Extendicare. ALC disclosed in their 10-Q that they might, they violate debt covenants at year end. Our leases with ALC/Extendicare do not provide that this potential default will be a default under our leases. ALC also stated in their 10-Q that it is working to get waiver. ALC's selling asset it could give more security to the banks, it could pay higher interest, there appears to be ways to negotiate a waiver.
There is no reason to believe that the assets will be in a diminished physical condition at the termination of our master leases. There is no reason to believe that LTC will not be able to collect the same is not more rental income when the master lease terminates on the properties that are now covering 1.2 time after 5% management fee and have been operated under a challenging turnaround environment.
Furthermore, Simpson explained that ALC is making progress with its new management team:
I'm sure many of you who have listen to the recent ALC Conference Call, Dr. Roadman, the Interim CEO discussed many improvements that he and his team have implemented and will implement at ALC. They indicated that they are making progress with lending relationship with regulators, employees and residence.
Here is a snapshot of LTC's occupancy including and excluding the impact of ALC:
Here is a snapshot of LTC's EBITDAR coverage including and excluding the impact of ALC.
What I Like About LTC?
One thing that I noticed when I was writing the "Bond-Proxy" REIT article is that LTC has an exceptionally conservative balance sheet. Compared with all 18 REITs that I researched in that article, LTC had the second lowest debt-to-market cap ratio (18.1%). Note: National Health Investors (NHI) had the lowest at 11.9%.
Another positive for LTC is the fact that the company has just a small fraction of secured debt - just 1.2%. That is also the second lowest REIT just beat out by National Retail Properties (NNN) with secured debt of just 0.7%.
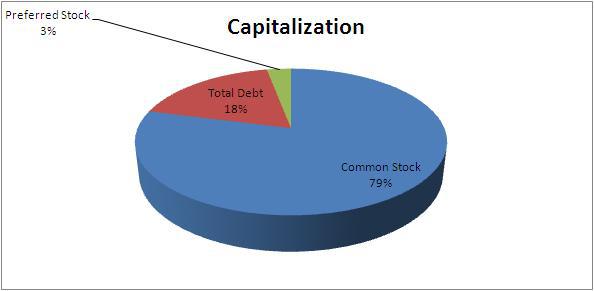
LTC's capitalization consists of around $971 million in common stock, $38.5 million in preferred stock (Series C), and total debt of around $224 million.
(click to enlarge)
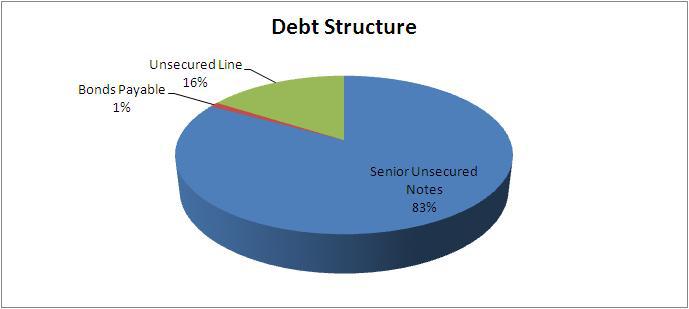
The debt is broken down as follows: $35 million in bank borrowings (LIBOR + 125 bps), $185.8 million in senior secured notes (weighted average rate is 5.17%), and bonds payable (weighted average rate is 2.21%).
(click to enlarge)
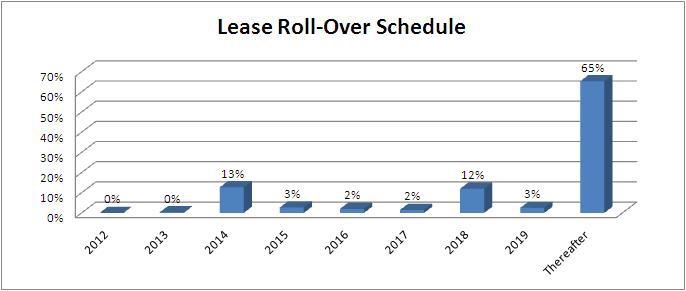
LTC has no meaningful debt maturities until 2015 ($29.166 million in notes) and the company's lease roll-overs are fairly staggered.
(click to enlarge)
So How Does LTC Stack Up Against the Other Net Lease Players?
First, let's take a look at LTC, compared with the healthcare peers.
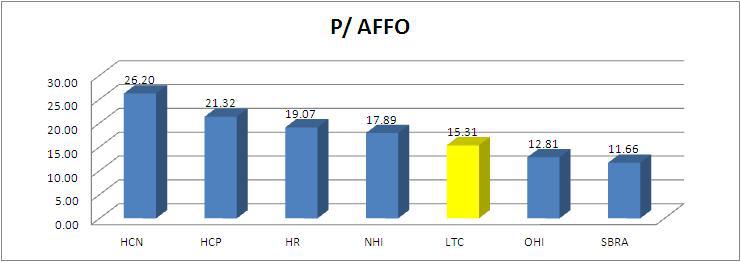
LTC's shares are trading at $34.85 with a market cap of $1.063 billion. The latest (Q3-12) AFFO is $17.362 million. Compared with the direct peer group, LTC is trading at a fair multiple.
(click to enlarge)
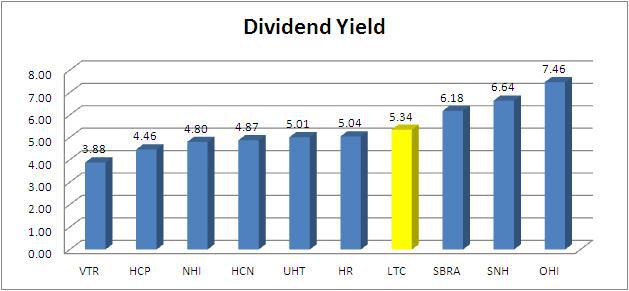
The current dividend yield is 5.34% and that puts LTC right in the middle of the pack (average of this peer group is 5.37%).
(click to enlarge)
Now, let's take a look at how LTC compares with the broader "bond-proxy" group. As you can see, there is nothing great, just in the middle of the pack.
Now Let's Compare to the Big Bad Dividend Machine
OK. Now I can put this bond-proxy example to work as a "real life" example. As I explained in that article (referenced above):
My theory of Realty Income (O) as a "bond-proxy" alternative goes that bonds are meant to stabilize your portfolio and dampen the volatility inherent with the violent swings of the stock market. They are also meant to provide diversification benefits by zigging when stocks zag and vice versa. In this way, bonds can significantly reduce the risk of your portfolio without reducing returns too much. Realty Income seems to meet both of these requirements with higher returns and income than the average bond fund.
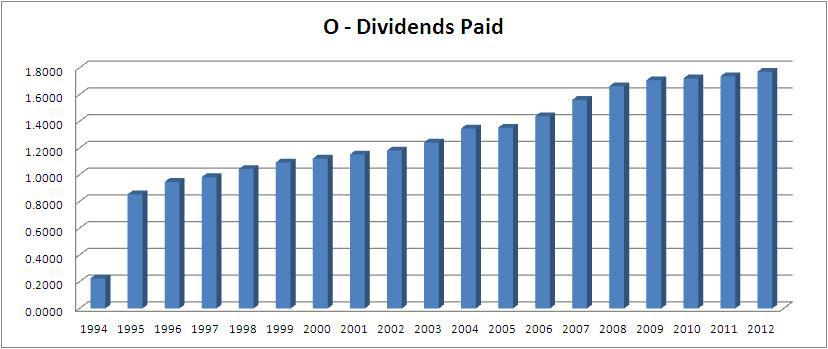
So as Realty Income as the "bond-proxy" benchmark, let's take a look at the "dividend machine's" dividend payout history:
(click to enlarge)
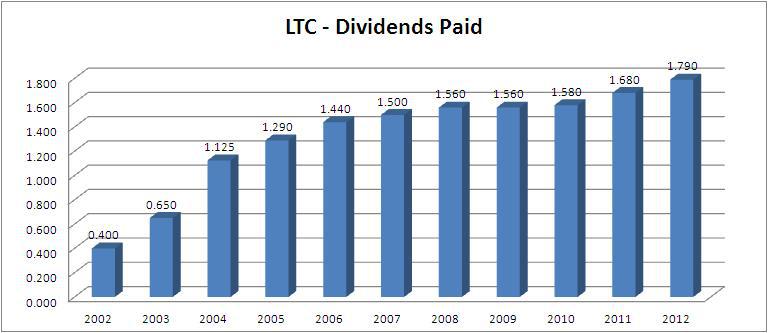
Now that is a smooth-looking dividend chart… how does that compare with LTC?
(click to enlarge)
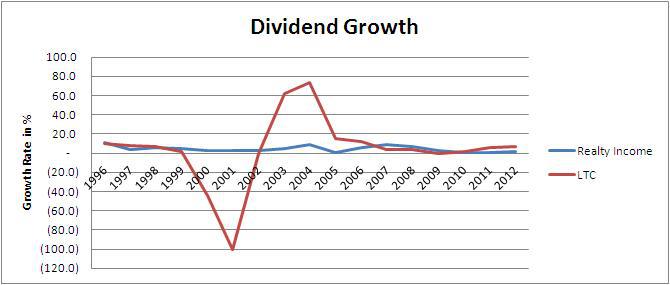
Oops. Fumble. As you see, in 2001 there is no love for LTC. Not one quarter of mailbox money. Now, in all fairness, LTC has rebounded nicely and in fact, the company started paying monthly dividends in 2005 (the company was paying quarterly before that) and during the third quarter (of 2012), LTC increased its monthly common dividend from $14.05 per share to $15.05 per share.
(click to enlarge)
But let's take a look at the historical dividend growth of LTC comparedwith a stalwart "monthly dividend machine".
(click to enlarge)
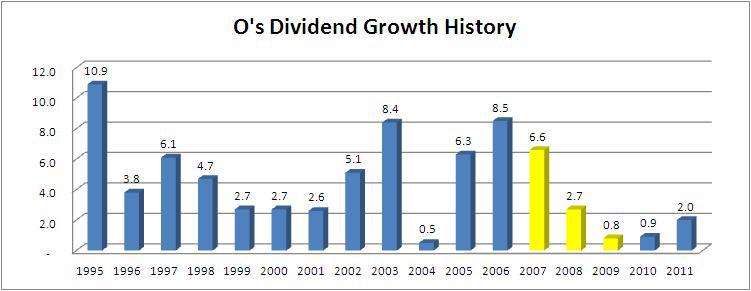
Drilling down further, take a look at Realty Income's growth history: It's not the best growth chart I have ever seen but pay special attention to the years that I highlighted in yellow - the years we call the Great Recession. While most REITs were busy cutting or suspending dividends (only 11 REITs increased), the "monthly dividend machine" kept on ticking….
(click to enlarge)
Does LTC Fit Inside My Box?
Overall, I like LTC. As noted above, I was initially attracted to the REIT because of the very well-positioned balance sheet. In addition, I like the fact that the company has not cuts its dividend in 10 straight years.
However, the sector is clearly at risk and its primary tenant, Assisted Living Concepts, is having difficulties. When compared with the broad "bond-proxy" net lease group, I feel as though there are too many other REITs that provide a much more attractive risk-adjusted return. Specifically, there is less than a 100 bps difference in dividend yield between Realty Income and LTC.
Consider this. Would you rather own the "dividend machine," an investment grade rated (S&P: BBB) REIT with over 2,838 individual net lease properties that consist of 144 different tenants and 44 categories, (that portfolio will likely grow to 3,345 properties with the merger of ARCT) that pays 4.50% OR would you prefer to own LTC with 207 properties and 32 tenants (many of which are under pressure due to Obamacare) that pays a 5.34% dividend?
In addition, I think there are better ways to play healthcare. As I have written in previous article, I like Healthcare Trust of America (HTA) - paying a 5.84% dividend, Medical Properties Trust (MPW) - paying a 6.81% dividend, or Omega Healthcare - paying a 7.46% dividend.
(click to enlarge)
Alternatively, if LTC shares drop below $25.00, you are back in bargain range (analyst consensus is $26.75 to $27.50) or perhaps you should consider the preferred shares (Series C) with an 8.5% yield.
(click to enlarge)
For those who have been invested in LTC for a while, it may be time to look at rebalancing the portfolio and riding out the Assisted Living Concepts risk by finding a more risk-aligned healthcare REIT. Given the continued risk of the highest risk healthcare sector (long-term care), I believe there are better alternatives that will help you "sleep well at night."
Source: SNL Financial and LTC Presentation (November 2012)
Companies mentioned: (SBRA), (HR), (SNH), (HCP), (VTR), (UHT), (LSE), (LXP), (OLP), (ARCP), (MNR), (GTY), (WPC), (EPR), (GOV), (ARCT), (ADC).
 
 
Support : Creating Website | Johny Template | Mas Template
Copyright © 2011. Economic Challenges Articles - All Rights Reserved
Template Created by Creating Website Published by Mas Template
Proudly powered by Blogger